An ordinary annuity is a financial product that can provide a series of payments over time. For people planning retirement, it may become one part of a broader income strategy alongside a pension, Social Security, and personal savings.
Before deciding whether an annuity fits your situation, it’s important to understand how it works, what benefits it may offer, and what limitations to consider.
Key Takeaways!
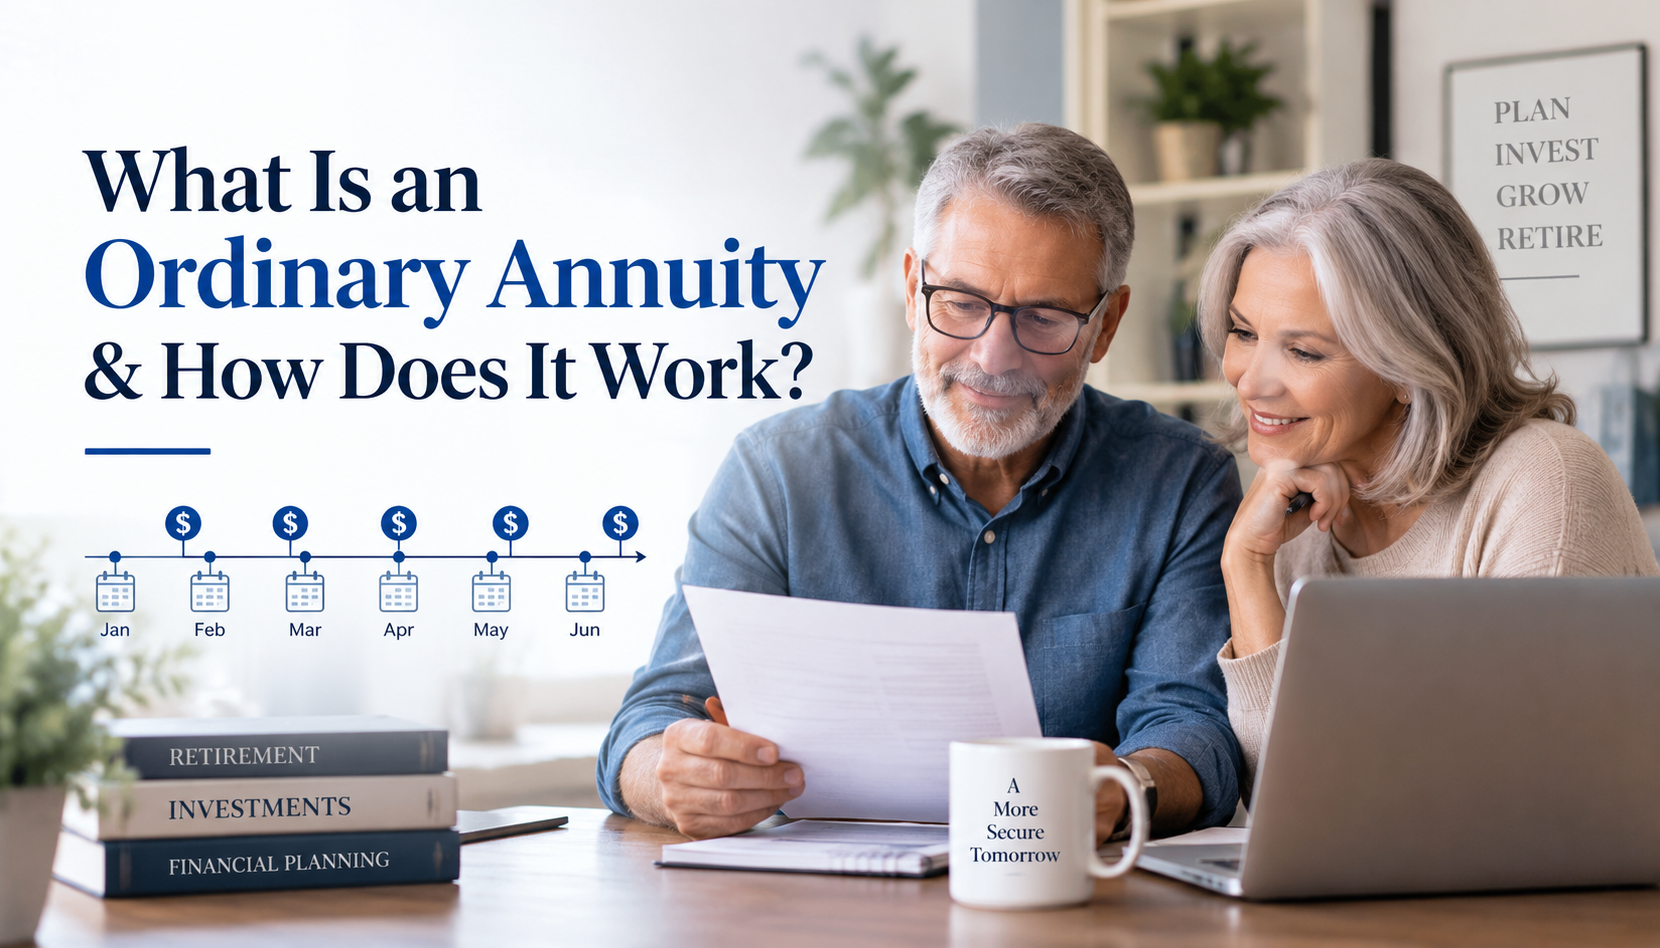
An ordinary annuity makes payments at the end of each payment period.
Payments may be monthly, quarterly, semi-annually, or annually.
Fixed annuities generally provide predictable payments, while variable annuities depend on investment performance.
Annuities may offer tax-deferred growth, but fees, surrender charges, and limited liquidity can apply.
An annuity is a financial contract that provides a series of payments over a specified period. An ordinary annuity makes payments at the end of each payment period, unlike an annuity due, which pays at the beginning of each period.
Common payment schedules include:
Monthly
Quarterly
Semi-annually
Annually
The payment amount, interest rate, and payment period are generally established when the contract is issued.
Fixed Annuity
A fixed annuity typically provides a predetermined interest rate and predictable payments, making future income easier to estimate.
Variable Annuity
A variable annuity invests in underlying investment options, so future payments may rise or fall depending on market performance.
Suppose someone contributes $500 each month for 20 years into an annuity earning a fixed interest rate. Each contribution is added to the account, and interest is applied according to the contract’s terms.
Over time, the combination of regular contributions and compounded earnings may increase the account’s value, although actual results depend on the specific annuity contract.
Ordinary Annuity Formula
Two common calculations are used when evaluating annuities.
Present Value
Future Value
Where:
PMT = Payment each period
r = Interest rate per period
n = Number of payment periods
These formulas can help estimate future or present values, but actual annuity contracts may include additional features and limitations.
An annuity may become part of a retirement income strategy for some individuals because it can provide scheduled payments after retirement.
Potential benefits include:
Predictable income (with fixed annuities)
Tax-deferred growth until withdrawals
Long-term savings discipline through regular contributions
Whether an annuity is appropriate depends on individual circumstances, retirement goals, and the specific contract.
Potential Drawbacks
Annuities also have important trade-offs.
Limited Liquidity
Many contracts include surrender periods or restrictions on accessing funds early.
Fixed Payment Structure
Some annuities provide limited flexibility once payment terms are established.
Fees
Depending on the product, administrative fees, investment expenses, and surrender charges may reduce overall returns.
Common Examples of Ordinary Annuities
The concept of an ordinary annuity also appears in everyday financial situations involving regular end-of-period payments.
Examples include:
Mortgage payments
Car loan repayments
Rental payments
These examples illustrate the payment timing concept rather than representing retirement annuity contracts themselves.
An ordinary annuity may become one piece of a broader retirement strategy, but it should generally be considered alongside other retirement resources such as:
Pension benefits
Social Security
Retirement accounts
Personal savings
Investments
Understanding how these resources work together can help create a more complete retirement income plan.
An ordinary annuity is a financial product that provides scheduled payments at the end of each payment period. For some people, it may offer predictable income and tax-deferred growth, while others may need to weigh fees, liquidity restrictions, and contract terms carefully.
States Benefit Center provides educational resources to help state employees better understand retirement topics and connect with independent professionals who can discuss retirement planning based on their qualifications and licensing.
This article is for educational purposes only and does not constitute individualized financial, tax, investment, or legal advice. Always review the terms of any annuity contract and consult appropriately qualified professionals before making important financial decisions.